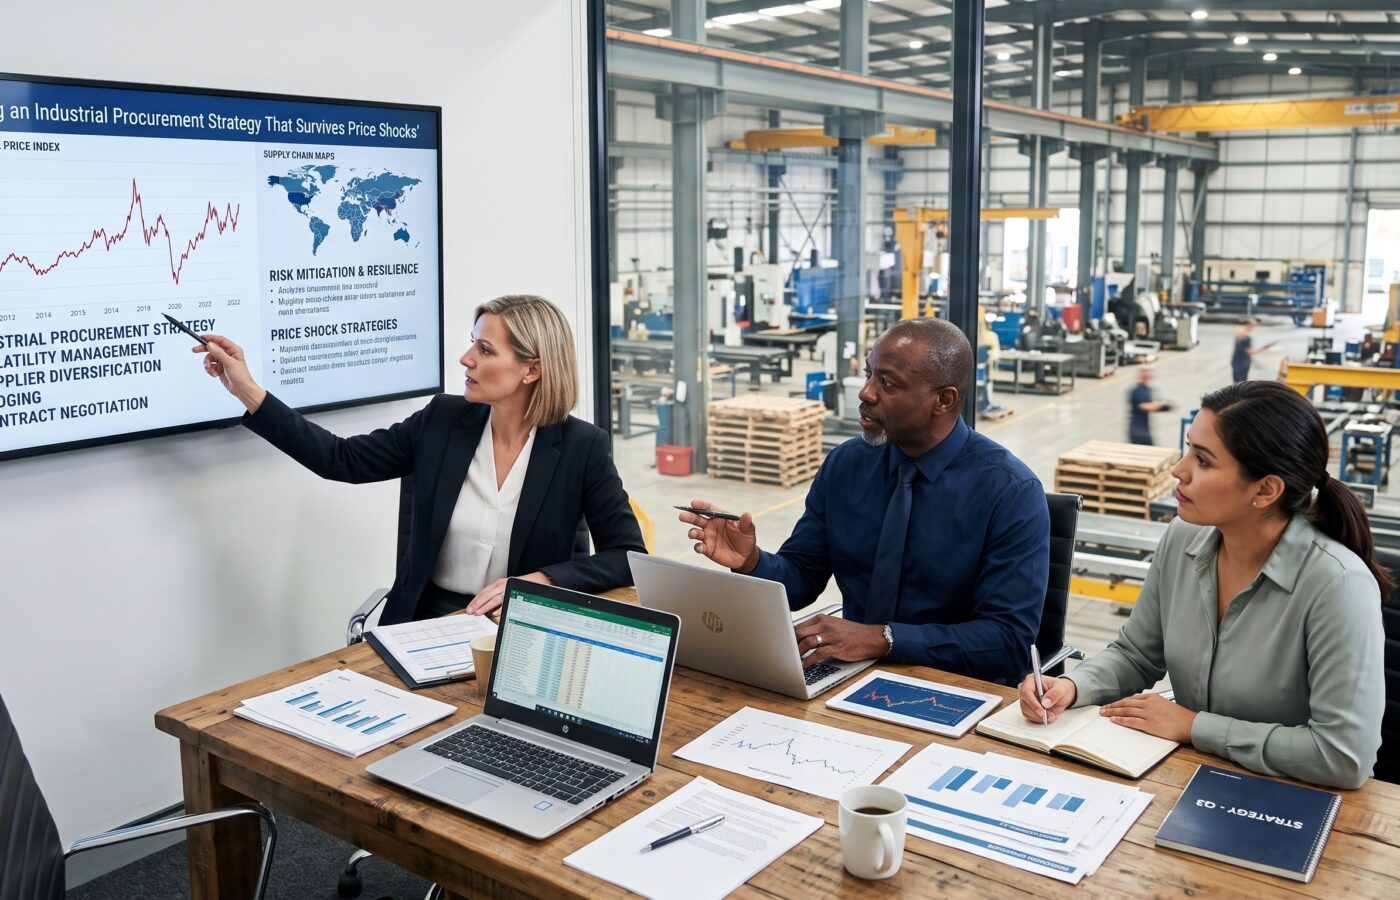
Building an Industrial Procurement Strategy That Survives Price Shocks
I have spent close to twenty years buying materials and negotiating contracts, building and rebuilding an industrial procurement strategy for one manufacturer after another. Part of that job is explaining to nervous executives why a resin or a steel index just moved 30 percent in a single quarter. Somewhere in that stretch, my job title changed. I went from purchasing manager to Head of Procurement, then to Chief Procurement Officer. The title changed. The core problem never did. Prices move. They rarely move in your favor at the moment you need them to hold steady.
What follows isn’t a textbook framework. It’s the industrial procurement strategy I actually use. I built it from a handful of very expensive mistakes. I also got a few decisions right, for reasons I didn’t fully understand until years later. If you buy raw materials, components, or industrial services for a living, you’ll probably recognize most of this.
Why Price Shocks Keep Catching Procurement Teams Off Guard
Every few years someone on my team asks why we didn’t see a price spike coming. The honest answer is usually that we did see it coming. We just saw it three weeks too late. Our visibility into supplier cost structures stopped at the invoice.
The unit price hides the real story
Most industrial procurement teams still run on a single number: the quoted unit price. That number hides everything that actually drives volatility. The freight surcharge tied to a bunker fuel index disappears into it. So does the energy cost baked into a smelting process. So does the labor contract expiring at a supplier’s plant in six months. When one of those drivers moves, the unit price moves with it. By the time it shows up on a purchase order, you’re reacting instead of planning.
I’ve come to think of price shocks less as sudden events and more as delayed notifications. The shock already happened somewhere upstream. What you’re feeling is the lag. An industrial procurement strategy built to survive shocks has to close that lag. That means going further into the supply chain than most teams are comfortable going.
Why industrial buyers get hit harder
There’s a structural reason shocks hit industrial buyers harder than retail or services buyers. Industrial inputs like metals, resins, energy, and specialty chemicals are commodities. They trade on markets. Those markets respond to geopolitics, weather, and speculation, not just supply and demand. A drought in one country can move the price of a component sourced from a completely different continent. Both draw on the same feedstock, even if the connection isn’t obvious. If your sourcing team only tracks its own supplier relationships, and ignores the commodity markets underneath them, you’re always a step behind.
Start With Total Cost Visibility, Not Just Unit Price
Getting suppliers to open their books
The first real change I made, back when I was running a mid sized sourcing team, was simple. I stopped letting suppliers quote a single all in number. We started requiring a cost breakdown: raw material, conversion cost, freight, packaging, margin. It was an uncomfortable conversation with some long standing suppliers. A few pushed back hard. But the ones willing to open the books became our most valuable partners. We could finally see which line items were volatile and which were stable.
Indexing the volatile pieces
Once you have that breakdown, you can index the volatile components to a public benchmark. Say aluminum makes up 40 percent of a part’s cost. You tie that portion of the price to a published aluminum index. The rest floats only with mutually agreed cost changes, like labor rate adjustments reviewed annually. This does two things. It stops you paying a hidden margin buffer that a supplier built in “just in case” prices moved. It also protects the supplier from absorbing losses they can’t sustain. That keeps them financially healthy enough to keep supplying you when things get tight. This kind of total cost visibility is the backbone of any real industrial procurement strategy.
I’ll be direct about something a lot of procurement content skips. Total cost visibility requires trust, and trust takes years to build. It’s not a clause you insert into a template contract. Suppliers open their cost structure to buyers who have proven they won’t use that information to squeeze margin every quarter. If your reputation is that of a buyer who beats up every supplier on price, don’t expect open books. You’ll get sanitized numbers designed to protect them from you. That defeats the entire purpose.
Build a Supplier Base That Can Flex Under Pressure
This is where an industrial procurement strategy gets tested in the real world, not just on paper.
Why single sourcing fails when it matters most
Single sourcing feels efficient right up until your one supplier has a fire, a labor strike, or a force majeure event. Then you have no fallback. I learned this the expensive way early in my career. A sole source component supplier went through a plant flood. We had six weeks of finished goods we couldn’t ship. That gap cost more than a decade of the “savings” we’d gotten from consolidating volume with a single vendor.
Dual sourcing, or in some categories multi sourcing across three or more qualified suppliers, costs you some economies of scale. I won’t pretend otherwise. But the resilience it buys during a price shock is worth more than the incremental discount from concentrating all your volume with one vendor. When one supplier’s region gets hit with an energy crisis or a tariff, you can shift volume instead of absorbing the full impact.
Making dual sourcing real, not just paperwork
The part people get wrong is treating dual sourcing as a paperwork exercise. They qualify a backup supplier and then never actually run volume through them. A backup you’ve never used isn’t a backup, it’s a hope. We keep a minimum of 15 to 20 percent of volume running through the secondary source at all times in our critical categories. That way, when we need to flex to 50 or 60 percent overnight, the supplier already has our specs and our quality requirements. They already have a working relationship with our plant floor. Ramping a cold supplier during a crisis takes months. Ramping a warm one takes weeks.
Spread matters as much as headcount
Geographic diversification matters just as much as supplier count. Two suppliers in the same earthquake zone don’t give you real redundancy. Neither do two suppliers in a country facing the same export restriction. They give you the illusion of it. When we map our supply base now, we look at supplier concentration by region, not just by company name.
Use Contracts as Shock Absorbers
A lot of procurement teams treat contracts as a one time negotiation event. I treat mine as a living risk management tool. The clauses that matter most for surviving price shocks aren’t the ones that lock in the lowest price today. They’re the ones that define what happens when the market moves. Getting this right is a core part of any industrial procurement strategy.
Building in price adjustment mechanisms
Index linked pricing, which I mentioned above, is one piece. Another is a price adjustment cadence both sides agree to in advance. Think quarterly reviews tied to a named published index. That beats ad hoc renegotiation whenever a supplier feels like asking. Ad hoc renegotiation almost always favors whichever side has more leverage at that exact moment. During a shock, that’s rarely you.
I also negotiate volume flexibility bands into contracts wherever I can. This means the ability to shift plus or minus 20 percent of forecasted volume without penalty. This matters more than people expect, because demand volatility and price volatility often hit at the same time. If a shock forces your own customers to pull back orders, you don’t want a take or pay clause locking you into volume you can no longer sell.
Force majeure clauses that actually hold up
Force majeure language deserves more attention than it typically gets too. Generic force majeure clauses copied from a template rarely hold up when you actually need them. We now specify what qualifies as force majeure. Documentation requirements are spelled out too. And so is the supplier’s obligation to notify us and propose mitigation, instead of letting them walk away from the contract with no consequence.
Financial Hedging Versus Operational Hedging
There are two fundamentally different ways to hedge against commodity price volatility. Conflating them is a mistake I see constantly, including one I made myself early on.
When financial hedging actually works
Financial hedging uses instruments like futures contracts, swaps, or options to lock in a price for a commodity you’ll need in the future. It works well when you’re buying a true commodity with a liquid, transparent futures market. Think copper, aluminum, or crude oil derivatives like fuel. It requires treasury expertise most procurement teams don’t have in house. That means partnering closely with finance, rather than trying to run hedging programs solo. I’ve seen procurement leaders attempt financial hedging without that partnership. They end up creating speculative exposure instead of reducing risk, which is exactly backwards from the intent.
Why operational hedging should be the default
Operational hedging is everything else: dual sourcing, inventory buffers, flexible contracts, substitutable materials, regional diversification. It doesn’t require a trading desk. It does require planning ahead of the volatility rather than reacting to it.
My view, after watching both approaches play out, is simple. Operational hedging should be the default for most industrial buyers. Financial hedging should be reserved for inputs where you have real volume and real market liquidity. You also need real internal expertise to manage the position. Trying to financially hedge a niche specialty chemical with no liquid futures market wastes effort. Trying to operationally hedge a widely traded metal, when you have the sophistication to hedge financially, leaves protection on the table. Choosing the right mix of the two is one of the more technical judgment calls inside an industrial procurement strategy.
Build Inventory Buffers Without Bloating Working Capital
Every finance leader I’ve worked with wants inventory as low as possible. Every operations leader wants enough buffer that a supply hiccup never stops the line. Procurement sits directly in the middle of that tension. During a price shock, the tension gets worse. Holding more inventory ahead of an expected price increase can actually save money. Finance still sees it as cash tied up on a balance sheet. Managing that tension well is part of what makes an industrial procurement strategy sustainable, not just resilient.
Separating safety stock from opportunistic buying
The way I’ve resolved this internally is by separating true safety stock from opportunistic buying. Safety stock is calculated from lead time variability and demand variability for a given item. It’s a defensible number that operations and finance can both audit. Opportunistic buying is different. It’s a separate, smaller pool of budget authority. I hold it specifically to act when we have a strong signal that a price increase is imminent. It lets us pull forward purchases without disrupting the base inventory model everyone has already agreed to.
This only works if you’re honest about the signal quality. I do not chase every rumor of a price increase. I’ve been burned buying ahead of an increase that never materialized. That tied up cash and warehouse space for nothing. I’m only willing to act opportunistically in categories where I have strong index correlation and historical volatility data. I need a clear enough view of the supply and demand balance to have real conviction, not just anxiety.
Make Data and Forecasting Part of the Procurement Function
For most of my career, procurement forecasting meant looking at last year’s spend and adjusting for expected volume changes. That’s not forecasting, that’s extrapolation. It tells you nothing about whether the market underneath your spend is about to move.
Tracking the leading indicators
We now track leading indicators for every major spend category. That includes input commodity prices, energy costs in supplier regions, freight rates, currency movements, and capacity utilization. None of this requires a massive data science team. A lot of it is publicly available through industry associations and government statistics agencies. What it requires is someone on the team whose explicit job is watching these indicators. Their job is flagging when something moves outside its normal range, rather than assuming that’s someone else’s job.
The payoff shows up in negotiation timing as much as anything else. Say you know a supplier’s key input cost is trending down. You have a much stronger position asking for a price review. Otherwise you’re waiting for them to volunteer that information, which they rarely rush to do.
Get Finance and Operations in the Room Early
I’ve watched more procurement strategies fail from lack of internal alignment than from any external market event. If finance doesn’t understand why you’re holding extra safety stock, they’ll flag it as inventory bloat in the next budget review. Then they’ll pressure you to draw it down at exactly the wrong time. If operations doesn’t trust your supplier diversification plan, they’ll quietly keep favoring the incumbent supplier. That happens regardless of what the contract says, because that’s the relationship they know.
The procurement strategies that actually hold up under pressure are built with finance and operations at the table from the start. I run a quarterly risk review with both functions. We walk through category level exposure, upcoming contract renewals, and any indicators trending in a concerning direction. It’s not a glamorous meeting. It’s also the single highest leverage hour I spend each quarter. When a shock actually hits, nobody is hearing about our mitigation plan for the first time.
What I’d Do Differently If I Were Starting Today
If I were rebuilding an industrial procurement strategy from scratch, I’d resist chasing the lowest unit price as the primary measure of success. It’s the easiest number to report up the chain. It’s also the number most likely to leave you exposed when a shock hits. The lowest price supplier is often the one who cut the most corners on redundancy and flexibility.
I’d also start building supplier relationships in adjacent regions before I needed them. That beats scrambling to qualify a new supplier under time pressure during an actual disruption. Supplier qualification done properly takes months. It means quality audits, trial runs, and a real understanding of a supplier’s financial stability. Doing it under crisis conditions means skipping steps you’ll regret skipping.
Finally, I’d invest earlier in the boring infrastructure. That means the spend visibility, the indexed contracts, the cross functional review cadence. I wouldn’t treat those as nice to have improvements for a quieter year. There is never a quieter year. There’s just the year before the next shock and the year after it.
Bringing It All Together
None of this eliminates volatility. Nothing does. Commodity markets, energy prices, and freight rates will keep moving for reasons outside your control. No procurement strategy, however well designed, changes that reality. What a strong industrial procurement strategy does is change how much of that volatility actually reaches your bottom line and your production line.
The teams that come through a price shock in reasonable shape are almost never the ones who guessed right about the market. They’re the ones who built total cost visibility. A flexible, geographically diversified supplier base was part of it. So were contracts that adjust instead of break. Their hedging approach matched the actual liquidity of the commodity. And finance and operations were aligned before the pressure hit, not during it. That’s not a secret formula. It’s what a durable industrial procurement strategy looks like in practice, built on discipline applied well before you need it.
Frequently Asked Questions
What is an industrial procurement strategy?
An industrial procurement strategy is the set of policies and practices a company uses to source raw materials, components, and services for industrial production. It covers supplier selection, contract structure, pricing mechanisms, inventory policy, and risk management, not just the act of placing purchase orders. For a broader framework overview, see ISM’s supplier risk guidance.
How can procurement teams prepare for sudden price shocks?
The most effective industrial procurement strategy combines a few things. It takes total cost visibility into supplier pricing, a diversified and geographically spread supplier base, contracts with built in price adjustment mechanisms, and leading indicator tracking for the commodities that drive your input costs. McKinsey’s research on inflation and volatility covers this in more depth.
What’s the difference between financial and operational hedging in procurement?
Financial hedging uses market instruments like futures and swaps to lock in a commodity price. It works best for liquid, exchange traded commodities. Operational hedging relies on non financial tactics like dual sourcing, inventory buffers, and flexible contracts. It’s accessible to most industrial buyers regardless of trading expertise. GEP’s commodity risk management guidance breaks down both approaches.
Is dual sourcing worth the extra cost compared to single sourcing?
In most critical categories, yes. The modest premium you pay for maintaining a second qualified supplier is generally far smaller than the cost of a full supply disruption. Gartner’s supply chain risk resources outline how leading organizations weigh this tradeoff.
How much safety stock should a manufacturer hold during volatile markets?
There’s no universal number. It depends on lead time variability, demand variability, and the volatility profile of each input. The more useful practice is separating calculated safety stock from opportunistic buying tied to specific price signals. Deloitte’s resilience research discusses inventory strategy alongside broader resilience planning.
Why do commodity price shocks affect industrial buyers more than other sectors?
Industrial inputs like metals, resins, and energy trade on global markets. Those markets respond to geopolitics, weather, and speculative trading as much as underlying supply and demand. A shock in one region or market can pass through to buyers with no direct exposure to the original event. ASCM’s insights on raw material sourcing explores this dynamic in more detail.
References
- McKinsey and Company. “Responding to inflation and volatility: Time for procurement to lead.” mckinsey.com
- McKinsey and Company. “Supply chain resilience in the face of change.” mckinsey.com
- Deloitte United Kingdom. “Procurement and supply chain resilience in the face of disruption.” deloitte.com
- Institute for Supply Management. “Identifying and Measuring Supplier Risk.” ismworld.org
- Gartner. “Top Supply Chain Risks and Mitigation Strategies.” gartner.com
- Association for Supply Chain Management (ASCM). “A New Perspective on Sourcing Raw Materials.” ascm.org
- GEP. “Commodity Risk Management: Finding Method in the Madness.” gep.com